Next week starts Spring Break for my kids. One full week of no school and if we're lucky maybe a trip for a night or two a few hours away. What to do with all that free time so there is no blood shed by the following Monday? Here is some ideas that I will be implementing during next week. Keeping my fingers crossed the kids will be as excited about them as I am.
- Movie Day: With Netflix, Hulu, and Redbox there is no excuse not to enjoy a day filled with nothing but PJs, popcorn and movies. If you want to get out to see a movie, check to see if there are any dollar theaters in your area or any Spring Break specials.
- Game Day: Break out the board games and deck of cards. Have a friendly marathon and competition with the winner either getting to pick what's for supper or the next day's frugal activity.
- Craft Day: This one will require lots of glue, markers, Popsicle sticks, fuzzy pom poms, googly eyes, old t-shirts, clay, etc. All of which can be purchased at a Dollar Store. Let your kids' creative juices run wild for the day. Display their artwork through the rest of Spring Break for all to see.
- Park/Museum Day: Spend a day at the park if weather permits. Have a picnic lunch, kick back and relax while the kids burn off some energy playing and exploring. If the weather is yucky take the fun inside to either an inside play area or check out your local museums.
- Cooking Day: Let each kid pick out a recipe or two and spend the day baking. Great teaching moment as well for smaller ones to learn fractions and kitchen safety.
- Water Day: If it's nice weather, spend the day running through sprinkler and having water balloon fights.
- Day Trips: If your budget permits, check out some of the neat attractions 2-3 hours from your home. You might be surprised what you will find.
I hope that at least some of the ideas can save someone their sanity during the Spring Break vacation.
Brought to you by:
Lifeway Personal Financial Coaching
No matter what a financial guru you are, these mistakes can happen to anyone. I even have to watch falling prey to a couple of them still.
- Impulse Buying: We all have done it from the candy bar at the check out counter to even a car (yes that's why I drive a Fuchsia Challenger). The best way to keep this from happening is to make a list when you go shopping, then make yourself a promise to stick to the list. Some of you may even need a shopping buddy (and I'm not talking about the kind that will tell you how cute you look in that sweater that's on sale). Take along a partner that will help you keep your shopping in check. Still can't do it? Then stay out of the problem store and either shop somewhere else or enlist someone to do the shopping for you. If you are using the cash envelope system then just put enough cash in the envelope to cover the needed items and leave your debit cards & checkbook at home.
- Not Doing Research: When you make big purchases, you should always research the product before you buy it. I'm not talking about walking around the showroom floor looking at the other items on display, but rather in depth research on the computer, books, magazines, friends, etc. Even though my Challenger was an impulse buy, I had actually been researching them for a couple of years. It just happened that the dealer got a rare color in I had been dreaming of owning and before I knew it, I was driving it off of the lot.
- Going into debt: When you have to go into debt to purchase an item (house excluded) then chances are you probably don't need the item. If it's something you do need, then that's a perfect example of why you should have an emergency fund in place. We live in a society of "hurry up and have it". Most of people's money problems could be lessened if they would practice a little self control (me included).
- Not Having A Plan: When you don't have a plan, a budget, you have no idea how much money you have, how much you need, or how much you've spent. When you have a plan, then you know where you were, where you are, and where you need to be. A budget will tell you where you need to cut back or spend more. It will show you where your problems areas are and where you are doing good. If you don't already do a budget every month, you need to start. Visit me over at Lifeway Personal Financial Coaching and I can show you how.
- Cosigning On A Loan: Think about this for a minute. If the bank doesn't think that this person is worthy of the loan on their own, it's because they don't think they will get their money. What makes you think they will pay if you cosign for them? Because it is your child? Your parents? If anything, that will make them even more likely to default and leave you holding the bag for the payments. By cosigning you are telling the lender when (not if) this person doesn't pay on the loan, you will pay off the loan for them. Do you really want another bill to pay?
- Not Having an EF: If you don't have an emergency fund then you need to start one NOW!! Ready, Set, Go!!!! Almost all debt for middle class America could be eliminated with just a simple $1000-2000 emergency fund. This would cover most car repairs, most household repairs, medical emergencies, etc. I'm not talking about a total overhaul of the engine, a new roof, or a heart transplant. I'm talking about every day stuff like, the fuel pump, water heater, or broken arm. Think about how many times you've laid plastic down to pay for these types of items and how long it took you to pay it off. I've used my EF many times. If I have to use it, I stop all debt repayment until it's built back up again and then restart debt reduction. Doesn't have to be anything fancy. Even hiding $1000 somewhere in your house will work......so long as you don't consider the pizza delivery an emergency!!

There ya go! Are you guilty of any of these? If so, just recognizing you need to work in that area is a major step. Think about what action steps are needed in order for you to correct the problems and then just start doing it. Don't expect to be perfect all the time because nobody is, but if you slip up pick yourself up and start at it again!
Brought to you by
Lifeway Personal Financial Coaching
Nothing makes a house feel like a home more than putting your personal touch on it. I was so excited when we purchased a brand new home last fall because it gave me a chance to put our mark on it right from the start. The challenge? Trying to do it without going into debt or emptying out our bank account. You see, we had a 3000+ sq ft modular home placed on an acre of land that was a mess (putting it kindly) and had to be cleared first.
This had been my inlaws home years ago. My mother-in-law passed away in 2006 and everything just sat until last year. Needless to say......we had our work cut out for us (and still do).
We
still have major landscaping to do, but that's all in time & with cash. We will do the majority of the work ourselves.
How I was able to decorate stylishly and keep it cheap while we also had the costs of cleaning up the land?
We moved from a 1400 sq ft home to one that was over 3000 sq ft PLUS we were blending our families together by having my husband's three kids come live with us as well. Can you say "freaking out"?
I had to take what I already had and make do or update but I also had to find new furniture as well. I put my Sherlock Holmes attire on and set to work.
Here is the living room before:
Living room after:
The furniture you see is the result of many hours of hunting for the right look at rock bottom prices. I didn't pay full price for any of the new items. The loveseat (will is a sleeper) was purchased at an auction for $50. With a $30 slip cover from Bed Bath & Beyond and a couple of clearance accent pillows from Kohls. I had a new sofa sleeper for under $100!! The accent chairs were purchased on ebay for $40 each. The accent table was my grandmother's and I threw a decorative table cover we found while cleaning out my MIL's place over it to hide some water circles. The telephone chair and big mirror with drawers came from the auction as well. The pictures on the wall were purchased from art.com on sale and then placed in half priced frams from Hobby Lobby. I did splurge on good paint and curtains from JC Penny. All the curtains and window accents in the house came from Penny's during a half off sale last summer. I had a 30% off coupon for all of the paint.
Dining Room before:
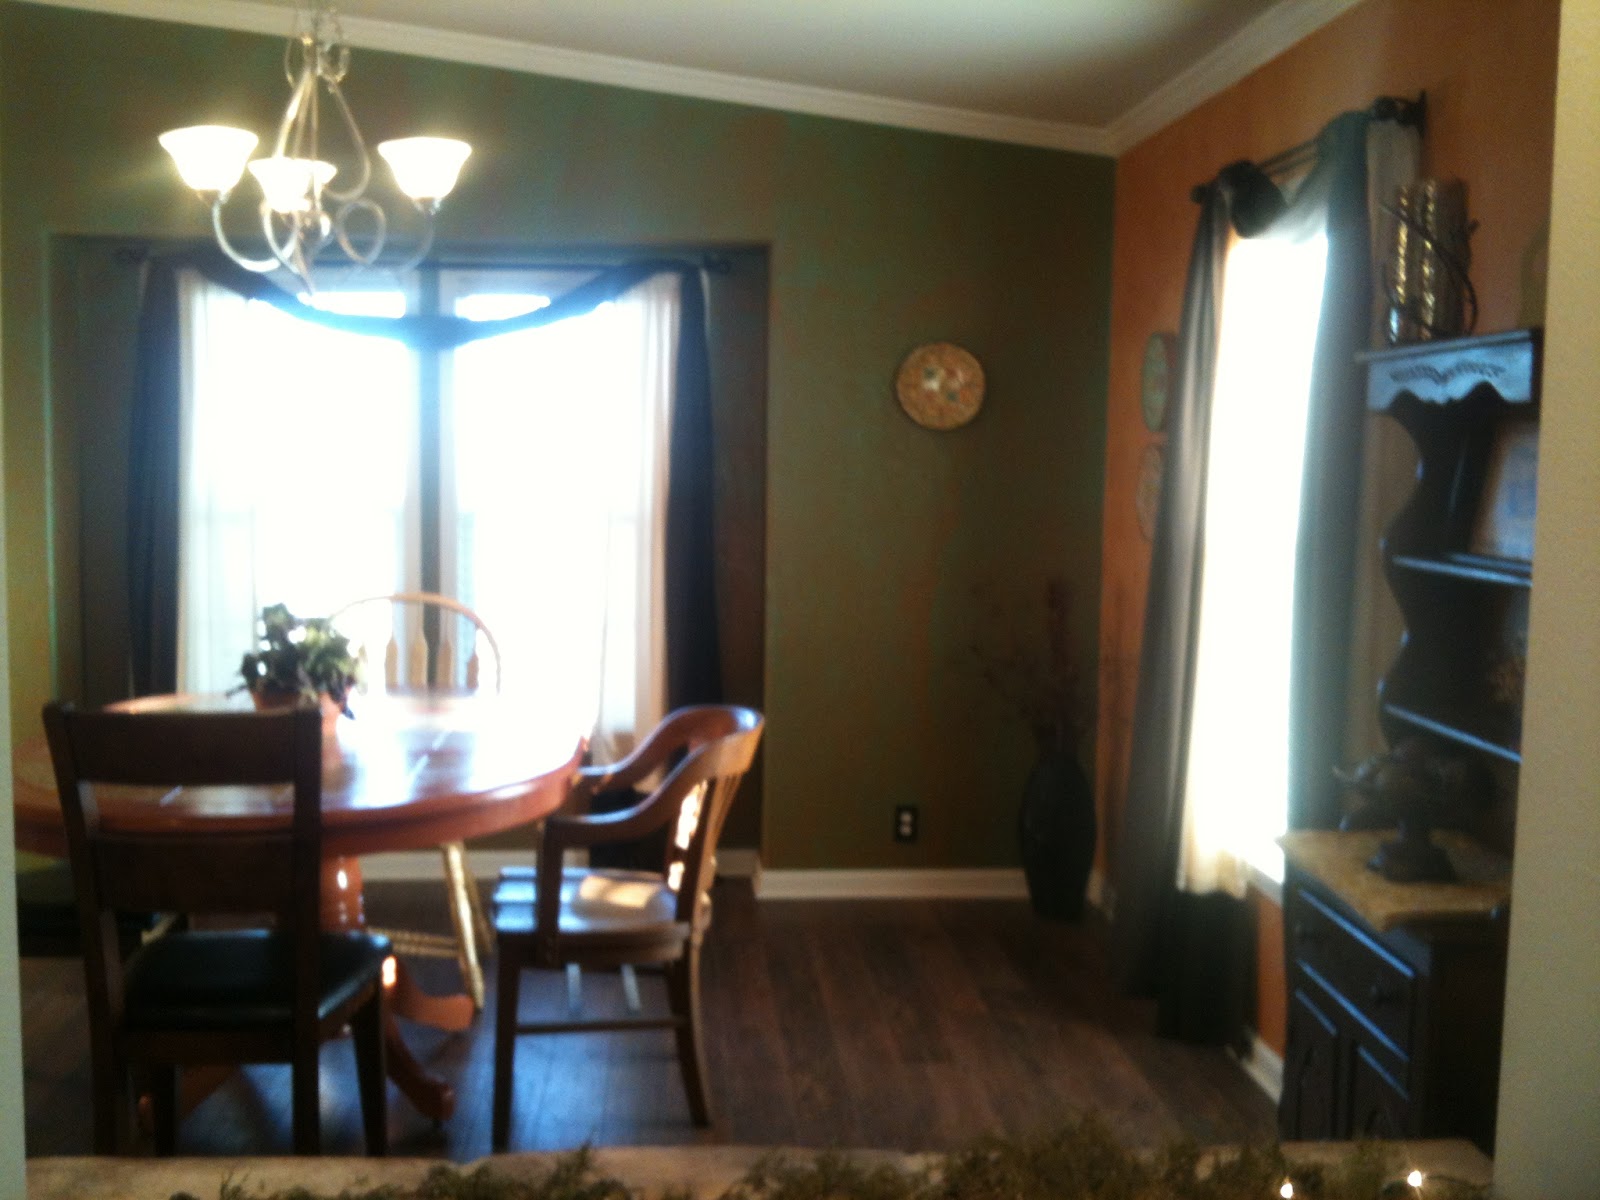
Dining Room after:
This is my favorite room because this it totally my style no compromising because of budget. I paid a friend less than $50 to texturize the far wall. I then used oil based paint and covered it with a copper glaze to give it a look of aged copper. I then used nothing but a rag and same glaze on the side walls giving them an appearance of an adobe wall. The small hutch was bought a a garage sale for $20. I painted it with a brown enamal. All accents were bought at Hobby Lobby on sale, WalMart on sale, or marked down at a second hand store. Again window dressing from JC Penny half price.
The dining room table is one of my favorite projects. It went from something like this:
To this:
I used a good primer made for finished wood so I woudn't spend forever sanding. After I painted the base coat on the wood, I used several colors & sponged them on the tiles. I covered everything with a few coats of poly eurothane to protect.
I also used this same technique to turn my son's dark brown wood bunk beds into something fit for a 10 year old girl and a 14 year old girl. A little sponging and some stencils and POOF:
My last project involved taking plain light wood bar stools I had and turning them into something unique to match our cool new bar. I used the crackle technique on them & stencil on the seat.
It's been six months since we moved in and it's still an ongoing project. We still have many blank walls waiting on the right inspiration or the right price. I want this home to reflect our tastes so when our friends walk in, they feel at home because our home gives off our personality.
With time and patience, you too can decorate cheaply and without going into debt.
Remember when everyone paid with cash and very few had credit cards? Me neither. My parents actually paid cash for everything & not once did I ever see them use a credit card until after I graduated high school. Sure they had the mandatory car & home loan, but other than that; it was cash.
In today's society it's the norm to pay with plastic. Since 2008 more people have started paying closer attention to their finances and spending habits. Unfortunately, most people are still spending more than they are bringing home and those pesky plastic cards are most of the problem.
It's not entirely the credit cards that are at fault, but debit cards can be just as bad for some people. It's been proven that when you swipe plastic at the checkout, your brain doesn't register the transaction. In other words, it doesn't hurt to spend money. On the contrary, you get a high from it. A feeling of power. A feeling that you are special. That is until you get the overdraft notice in the mail. How special are ya feeling now?
This is why for those who are just starting out taking control of their finances, I suggest using the cash envelope system. Want a real feeling of power and control?? Try handing the cashier cash for your purchase. That right. Just plop down those greenbacks and enjoy the feeling of power that you have cash to pay for your purchase. Not only do you know you have the money for the purchase, but so does everyone else standing close to you. Here are some pointers to using a cash envelope system.
Budget:
“Budget” can be a four-letter word for most people, but a budget is really nothing more than deciding how you’ll spend your income
before you actually spend a dime of it. If you’re not sure how much you spend in each budget category, track your expenses for a month and get an idea of the amount you'll need.
Choose Your Categories:
From your budget, go through and decide what you can pay cash for. The most common categories are: grocery, gas, personal care, clothing, entertainment, blow money, birthday & Christmas,etc.
These categories can vary and can be personalized to your families needs. Don't worry about setting up envelopes for bills you normally mail in or pay online. We are only worried about items that you could potentially overspend on if you use plastic.
Prepare Your Envelopes:
You've got your budget and decided on your envelope categories, now take out some regular paper envelopes and label one envelope per category. At the beginning of the month (or your pay period), withdraw your budgeted cash from the bank and separate it into the appropriate envelopes (i.e. $250 in the “gas” envelope).
As you get the hang of the envelope system, there are some really cool wallets that have envelopes in them. One such wallet is from Dave Ramsey. This is the one I use. Very stylish plus has a place for your checkbook and you can order envelope refills. You can view them
here.
Use Your Envelopes
Going shopping? Better take your envelope. Forgot your envelope? Better drive back home!
Whenever you spend money from one of your envelope categories, use the money from that envelope and replace it with your receipt. This will help you keep track of where your money has gone for the month.
Once It’s Gone…It’s Gone
Once you’ve spent all the money in your envelope, that's it.....you're done...no more....don't even think about it. It’s very tempting to pull out your debit card and keep right on spending. Make up your mind beforehand that once you’ve spent all the money in an envelope, you can’t spend any more money in that category until next month. That’s what makes the whole system work. It forces you to follow your budget.
This is why it's important to plan your spending, especially on groceries and gas. It really sucks to have a week left in the month and need groceries, but no more cash in the envelope. If this happens, it means you probably need to go back and rethink the amount of money you need in that envelope. It also means that money is gonna have to come out of another category. You have to BUDGET. You need more in one category means another category gets less.
(Something our government can't seem to grasp!)
Give It Time
It will take a few months to get your envelope system down. Don’t give up after a month or two if it’s still not working just right. You’ll get the hang of it and it will be so worth it once you see your debt go down and your go up…not to mention the peace of mind you’ll experience knowing you are controlling your money!
Now there's a feeling of power!!!!
Brought to by
Lifeway Personal Financial Coaching.
If you're like me, you want to save as much money as you can when you go to the grocery store. For some people it's a game, a sport. For me.....not so much.
I like to hit the sales, and I will use coupons now and again but you won't see me on the floor comparing sale ads or clipping tons of coupons. Truthfully, the small town I live in has two grocery stores and a Walmart Super Center. Not much choice. Not too friendly for couponing either. I usually stick to store brands on most items.
I found this link VERY useful though. This site has compiled a list of when items go on sale at the grocery stores. Not all stores are the same, but the information is excellent. I worked almost 3 years as a checker at a grocery store and discovered myself there was a cycle to the sales.
So, here is the link and Happy Savings!!!!


 Posted by: Michelle Osborn
 Filled in:
 Comments: